
en
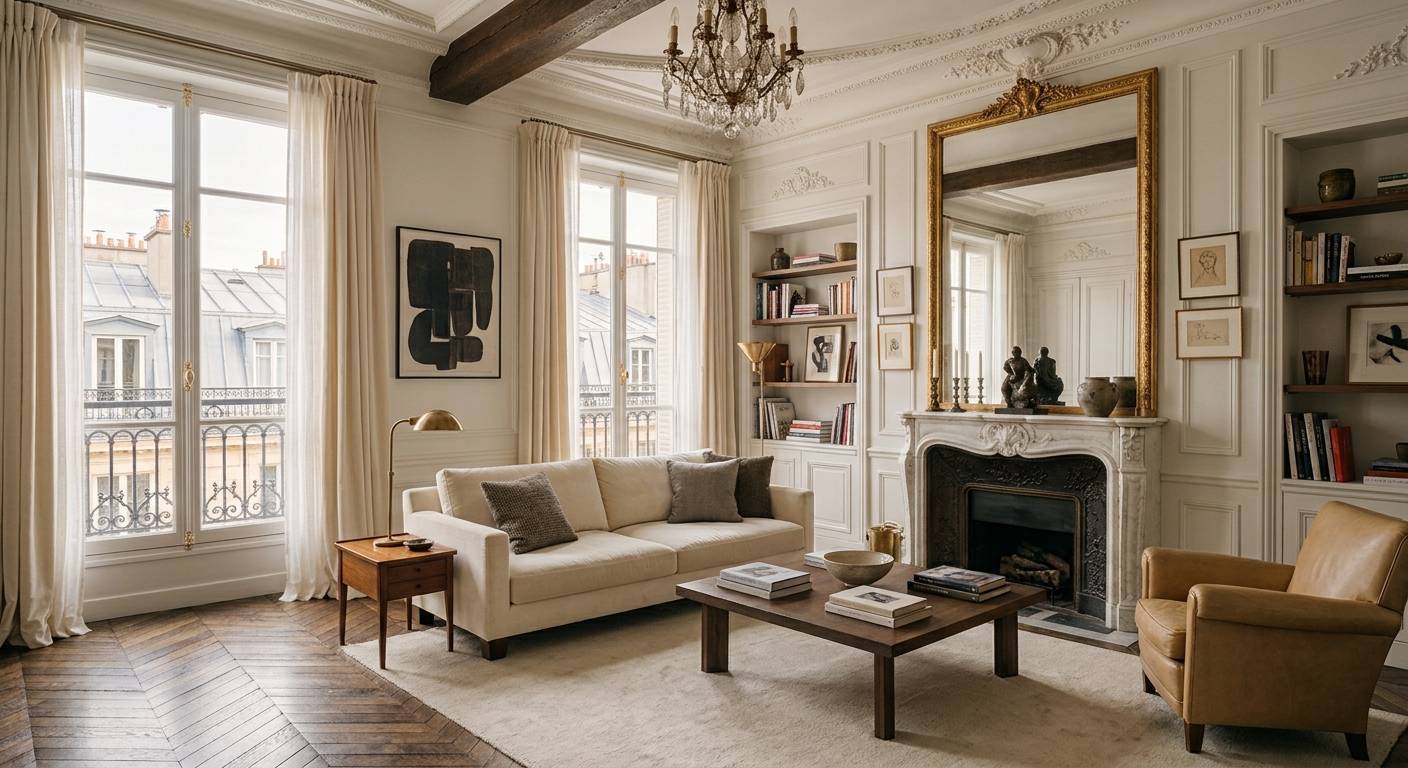
Fairway Luxury Real Estate analysis of mortgage rates, buyer financing and the Paris high-end property market in June and July 2026.
The European Central Bank raised its key interest rates by 25 basis points on June 11, 2026. At first glance, the news could worry both buyers and sellers: when the European Central Bank raises rates, the immediate assumption is that mortgages will become more expensive, budgets will shrink and negotiations will become tougher.
On the Paris market, however, the reality is more nuanced. At Fairway Luxury Real Estate, we are seeing that mortgage rates have not suddenly surged. Banks had largely anticipated the move, and the strongest applications continue to secure reasonable financing conditions. This does not mean the rate increase is irrelevant. It mainly confirms that the market remains selective, particularly for rental investors, buyers with limited down payments and transactions already close to debt-service limits.
The key issue in 2026 is therefore not simply the level of interest rates. It is the quality of the buyer's financing, the positioning of the property and the ability of both parties to assess the transaction in the context of current borrowing conditions.
On June 11, 2026, the European Central Bank increased its three key interest rates by 25 basis points. From June 17, 2026, the deposit facility rate rose to 2.25%, the main refinancing operations rate to 2.40% and the marginal lending facility rate to 2.65%. The decision aims to contain inflationary pressures and maintain inflation around the 2% target over the medium term.
For a property buyer, the immediate question is straightforward: does this increase automatically translate into higher mortgage rates? Not necessarily.
Key ECB rates influence banks' refinancing costs, but fixed-rate mortgages, which remain overwhelmingly dominant in France, do not react like an instantly priced financial product. Banks build their lending rates according to several parameters: the cost of money, competition between institutions, commercial objectives, risk level, borrower profile, down payment, income, disposable income after debt service and the quality of the property being financed.
In France, mortgage rates had already started to rise slightly before the ECB decision. The Banque de France reported that in April 2026, the average rate on new housing loans to individuals, excluding renegotiations, reached 3.22%, representing an increase of only 14 basis points since the beginning of the year.
In other words, part of the increase had already been incorporated into banking conditions. Banks therefore did not need to radically change their lending rates immediately after the ECB announcement.
There is also an important French factor: mortgages are overwhelmingly offered at fixed rates. This protects existing borrowers and limits panic effects. For a household that borrowed in 2022, 2023 or 2024 at a fixed rate, the monthly payment does not change. The issue mainly concerns new buyers, future refinancing and investors looking to structure a new transaction.
For someone buying a primary residence in Paris, the market is not closed. Banks continue to finance strong applications, particularly when the down payment is substantial, income is stable and disposable income remains comfortable.
In the areas where Fairway regularly operates — Paris 8th, 16th, 17th, 7th, Neuilly, Parc Monceau, Plaine Monceau, Ternes, Passy, Auteuil and Gros-Caillou — many buyers have significant down payments, sometimes resulting from a previous sale, a gift, expatriation or professional relocation. For these profiles, a 0.20 or 0.25 percentage-point change does not necessarily prevent a purchase. It can, however, change the choice between two properties or strengthen negotiations on an apartment with identifiable weaknesses.
This is particularly visible with family apartments between 90 and 150 square metres. A property on a high floor, with an elevator, good energy performance, a family-friendly layout, natural light and a sought-after address remains financeable and defensible. Conversely, a property requiring substantial work, with a weak energy rating, no elevator, significant overlooking or high condominium charges can become more sensitive to negotiation.
The interest rate does not create the discount on its own. It amplifies weaknesses that have already been identified during the viewing.
For primary residences, banks continue to have a strong commercial interest in lending. A mortgage remains a way to acquire and retain a banking client through account domiciliation, insurance, savings, investments and wealth-management relationships. This is particularly true for high-income professionals, senior executives, liberal professions, expatriates returning to France and families who already own property.
In the Paris luxury segment, some buyers are not simply looking for a mortgage rate. They are looking for an overall financing solution: bridge financing, coordination between a sale and a purchase, Lombard loans, interest-only structures, pledging of assets, cash-flow optimisation, co-ownership arrangements or purchases through a wealth-management company. The advertised 20-year mortgage rate therefore tells only part of the story.
"Our buyers in the 8th, 16th and Neuilly rarely think in terms of the interest rate alone. They think in terms of an overall financing solution — bridge financing, asset pledging or co-ownership — and that is precisely where preparation makes the difference between an accepted offer and one that drags on."
— Fairway Luxury Real Estate
The situation is different for rental investment. Investors face a more demanding equation: higher rates than during the 2020–2021 period, taxation, rent controls in Paris, energy performance requirements, renovation costs, condominium charges, property tax, potential vacancy and often compressed net yields.
The Relance logement tax incentive, also known as the Jeanbrun scheme, was introduced by the 2026 Finance Act and aims to encourage individuals to invest in rental property. It is presented as being available for three years and concerns certain investments in collective residential buildings, either new or existing properties involving renovation work.
On the Paris market, however, a tax incentive is not always enough to make an investment worthwhile. Investors need to examine net yield, location quality, future liquidity, renovation requirements, the condominium, energy performance, rental potential and the actual tax position after expenses. In Paris, many rental investments are not justified by immediate yield but by a long-term wealth strategy: capital preservation, inheritance planning, a future pied-à-terre, housing for a child, diversification or securing an asset in a rare location.
Consider a €1,000,000 mortgage over 20 years, excluding insurance.
The difference is approximately €129 per month, representing slightly more than €30,000 in additional interest over the full term of the loan.
For a high-end buyer with substantial income, this is not necessarily decisive. For an application already close to the HCSF debt-service limit, however, it can be enough to reduce purchasing capacity or cause financing to fall through.
This is where market experience matters. Two buyers can view the same €1.8 million apartment and have completely different relationships with the interest rate. One may purchase with a 50% down payment following a sale. The other may finance almost the entire transaction with a long-term mortgage. The first thinks primarily in terms of wealth quality. The second thinks in terms of monthly payments, debt-service ratio and bank approval.
The issue is therefore not only the headline level of interest rates. The real issue is banking selectivity.
The French High Council for Financial Stability continues to regulate mortgage lending around two major benchmarks: a maximum debt-service ratio of 35% and a maximum term of 25 years, subject to certain regulated flexibilities. The French Ministry of the Economy also points out that banks have a flexibility margin but remain free to approve or reject a loan, even when an application appears to meet the general criteria.
In practice, this means that a strong application is not simply about earning enough. It must present overall consistency: down payment, professional stability, existing debt, account management, a credible project, quality of the property, a justifiable purchase price, disposable income, potential renovation work and resale value.
For sellers, this reality needs to be incorporated from the moment the property is brought to market. A purchase offer does not have the same value depending on whether it comes from a cash buyer, a buyer with advanced bank approval or a buyer who only discovers their actual budget after viewing the property.
For a seller, the message is not: "rates are rising, so the price must be cut." That would be too simplistic.
The better question is whether the asking price is consistent with the depth of the solvent buyer pool. During periods of very low rates, certain weaknesses were easier for buyers to absorb: an average floor, an imperfect layout, renovation requirements, high charges, an average energy rating, no air conditioning or no outdoor space. When financing becomes more demanding, these characteristics have a greater impact on negotiations.
A perfectly located apartment, well presented, correctly priced and supported by a complete file can still attract buyers. An overpriced property, poorly documented or launched without a clear strategy, however, risks remaining on the market. The longer a property stays online, the more buyers tend to interpret its presence as a signal that the seller may be open to negotiation.
At Fairway, this market analysis is part of our valuation work from the outset. In Paris, price is not simply a matter of value per square metre. It is a balance between address, floor, light, layout, condition, condominium, energy performance, charges, rarity, liquidity and the ability of buyers to finance the project.
Before arranging multiple viewings, a buyer should have their financing assessed. Not simply through an online simulation, but with a mortgage broker or bank capable of testing the application under current market conditions.
This helps avoid three common mistakes:
In the current market, the most credible buyer is not necessarily the one making the highest offer. It is the one presenting the strongest combination of price, security and timing.
In this environment, the role of the real estate agent becomes central again. It is no longer enough to open a door and wait for an offer. Buyers need to be qualified, their financing understood, weak signals identified, banking objections anticipated and the transaction timeline secured.
This is the approach we apply at Fairway: being able to tell a seller that an offer may be slightly below expectations but is financially solid — or, conversely, that an attractive offer on paper relies on fragile financing. It also means explaining to a buyer why a property cannot be negotiated simply by invoking interest rates. A serious negotiation is based on precise elements: comparable sales, objective defects, renovation costs, time on the market, level of charges, energy performance, floor, exposure and condition of the condominium.
Interest rates are an argument. They are not proof.
Waiting can make sense if the project is not properly prepared, if the down payment is insufficient or if the purchase depends on an uncertain sale.
But waiting solely for rates to fall can also be risky. If rates fall tomorrow but prices rise again for rare properties, the buyer may not necessarily benefit. Conversely, if rates remain stable but a seller accepts a reasonable negotiation on a high-quality property, the opportunity may be attractive.
In Paris, buyers rarely purchase a family apartment, pied-à-terre or patrimonial property solely because a mortgage rate is attractive. They buy an address, a floor, light, a layout, rarity and a use.
The right question is therefore not simply: "Will mortgage rates fall?"
The right question is: "Is the property correctly valued under current financing conditions?"
Does an ECB rate increase automatically cause mortgage rates to rise?
No. Key interest rates influence banks' financing costs, but mortgages do not react instantly. Banks often anticipate monetary policy decisions and adjust their lending rates progressively.
Have mortgage rates increased significantly in 2026?
The increase remains moderate at this stage. The Banque de France reported an average rate of 3.22% for new housing loans in April 2026, representing an increase of 14 basis points since the beginning of the year.
Is it still possible to buy property in Paris with a mortgage?
Yes, particularly with a well-prepared application, sufficient down payment and a coherent debt-service capacity. Banks continue to finance primary residences, especially for strong borrower profiles.
Are rental investors more heavily affected?
Often, yes. Banks look more closely at profitability, overall debt, taxation, energy performance, charges and the overall wealth-management rationale of the investment. Rental investment remains possible, but it needs to be structured more carefully than during periods of very low rates.
Should a seller reduce the asking price because of higher rates?
Not automatically. However, sellers need to accept that buyers are making more detailed trade-offs. A property with visible defects, renovation requirements, poor energy performance or an ambitious asking price will be more exposed to negotiation.
How can a buyer secure a purchase offer in 2026?
The buyer should verify the down payment, financing structure, debt-service ratio, existence of bank approval or broker assessment, signing timeline, dependence on a previous sale and the consistency of the proposed price with the current market.
Do you have a property project in Paris?
Our Fairway advisors can help you assess the consistency of your financing and the true value of your property under current market conditions.
Sources
European Central Bank, monetary policy decision of June 11, 2026.
Banque de France, Panorama of household housing loans, April 2026.
High Council for Financial Stability, mortgage lending rules.
French Ministry of the Economy, how mortgage lending works and banking flexibility.
French Ministry of the Economy, Relance logement / Jeanbrun scheme.
 | Author of the article Hugues de Poulpiquet Fairway Luxury Real Estate · Real Estate Market Trained as a lawyer and founder of Fairway Luxury Real Estate, Hugues de Poulpiquet writes Fairway's market insights dedicated to the Paris real estate market, sales strategies and the valuation of high-end residential properties. |
Fairway Luxury Real Estate
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.